Why Exit Strategy Matters More Than Credit Score in Some Private Money Deals
Many borrowers come into private money discussions thinking their FICO score is the main hurdle. But in short-term real estate deals, that’s not the case. The real question isn’t “Does this person qualify like a bank would want?” It’s “How will the lender’s money get paid back, and how believable is that plan?” Credit score looks backward. Exit strategy points forward. The exit is what actually decides if the loan gets repaid on time.
This matters because private money funds deals banks won’t touch: fix-and-flips on tight schedules, bridge loans for properties not yet stabilized, transactional funding for double closes. These don’t fit into a 30-year amortization based on W-2s and credit history. Instead, it comes down to one sharp question: What happens at the end of this loan? Is that outcome realistic, given the property, the market, and the borrower’s plan?
What Credit Score Actually Tells a Lender (and What It Doesn’t)
Credit score looks at how someone handled debt in the past: payment history, utilization, derogatories, account age. That’s useful and not ignored in private lending. But it doesn’t say anything about the deal in front of you. It can’t tell you the after-repair value, whether the rehab budget is solid, if there’s a buyer lined up, or if the refinance lender has issued a term sheet.
A borrower with a 780 score but no real exit plan is riskier on a 9-month bridge loan than someone with a 650 score and a signed purchase contract. This isn’t theory, it’s how asset-based lending works. The property and exit plan are the real collateral. Credit score is secondary.
Why Private Lenders Underwrite the Exit, Not Just the Resume
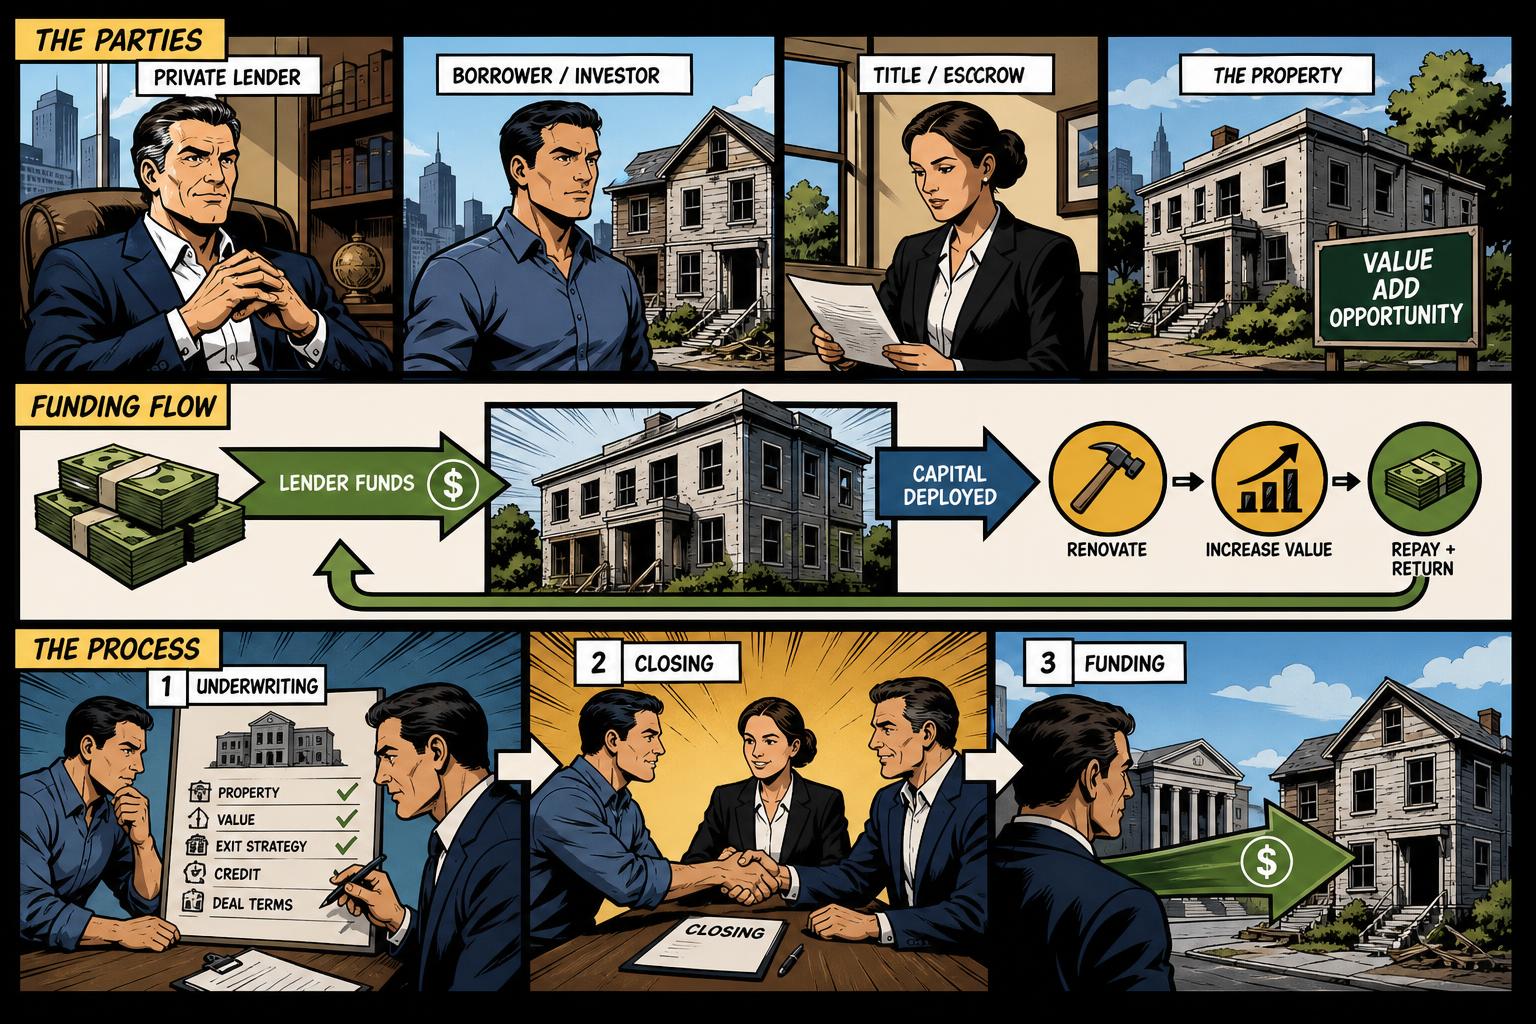
Private credit works differently than equity investing. As Carta explains, private credit has a set timeline: returns come from interest and principal, not selling equity years later. Private real estate lending works the same way. The lender isn’t betting on long-term appreciation or a distant liquidity event. They’re betting on a specific event: a sale closing, a refinance funding, or a construction draw paying off the loan.
That’s why exit strategy matters so much. If the repayment event is clear and realistic, the loan has a finish line. If it’s vague, “I’ll probably sell it, or maybe rent it, we’ll see”, the lender faces open-ended risk, no matter how good the borrower’s credit looks.
This also reveals a structural risk in the asset class. U.S. Bank notes that some private credit funds have had to limit investor withdrawals and rely on asset sales and loan repayments instead of steady redemptions. Scale that down to a single bridge loan: if the borrower’s exit stalls, the lender’s capital is stuck. The deal-level exit is the first line of defense, which is why it gets so much scrutiny.
The Three Exit Paths Private Money Lenders Actually See
Most short-term real estate loans end in one of three ways, each underwritten differently.
Sale. The borrower buys, renovates or stabilizes, then sells to a retail or investor buyer. Underwriting focuses on real comps, days-on-market trends, and whether the rehab scope and budget support the projected after-repair value. If the margin between all-in cost and projected sale price is thin, that’s a red flag, no matter the credit.
Refinance. The borrower uses short-term debt to acquire or stabilize, then refinances into a permanent loan, often DSCR or conventional, once the property is rent-ready or stabilized. This exit depends on whether the property will qualify for that refinance: occupancy, rent roll, debt-service coverage, and sometimes the borrower’s ability to qualify for the new loan. Borrowers strong on the asset but thin on personal credit or income sometimes need a boost to get through that second-stage underwriting. That’s where tradelines and credit sponsorship come in. It’s not about faking strength but making sure the exit lender’s criteria are met when it counts.
Payoff via sale of another asset or construction draw completion. Less common, but it happens in portfolio deals or new construction where the final draw or a separate liquidity event pays off the loan.
No matter the path, the underwriting question is the same: Is this exit likely to happen within the loan term, with some margin for delay?
When Credit Score Still Matters
Credit score isn’t irrelevant. It still matters in a few key cases:
- Loan sponsorship structures: When a credit-strong sponsor helps a weaker-credit operator qualify. The guide on loan sponsorship and equity partnerships explains how this works, and the multifamily syndication version shows how it scales up.
- Permanent refinance exits: If the eventual lender has a hard credit score floor, regardless of the private lender’s criteria.
- Repeat-borrower relationships: A track record of on-time payoffs (which loosely tracks with credit discipline) can affect pricing and leverage over time.
- Severely impaired credit with active collections or recent bankruptcy: This can signal operational instability, even if the deal’s exit looks solid.
Credit strength and exit strength aren’t opposites. They’re different layers of risk. A borrower can shore up a thin credit file through tradeline-based credit sponsorship or credit repair plus sponsorship while the main underwriting still rests on the exit. The point isn’t that credit never matters, it’s that in asset-based private lending, it rarely decides the deal alone.
Hypothetical Example: A Bridge Loan Exit Plan in Dallas, Texas
Here’s a hypothetical scenario, not a closed deal, to show how this works in underwriting.
An investor is looking at a single-family property in Dallas, Texas, listed at $310,000 in an active investor market on the south side. The plan: acquire with a short-term bridge loan, spend about $45,000 on cosmetic and systems renovations, and sell within seven months to a retail buyer. Total all-in cost: $375,000. Comps support an after-repair value near $460,000. That’s an $85,000 projected margin, about 18% of ARV, a workable cushion for a sale-exit deal.
The investor’s credit score is 640, below what most banks want for an investment property loan. In a bank’s world, that score might kill the deal. In private money, it’s just one data point. The bigger questions: Does the renovation scope match the comps? Is the contractor bid realistic for Dallas? Is there a credible backup exit, like a refinance-and-hold, if the sale takes longer than expected?
For a Dallas real estate investor, this is the practical difference with exit-based underwriting: The deal’s numbers and timeline carry the file, not the credit tier.
What I Would Review Before Funding This
On a deal like this, or any exit-driven private money request, here’s what gets examined before funding:
- Comparable sales supporting the projected exit value: Not list prices, but real closed comps within a realistic radius and timeframe.
- Renovation scope and budget: Checked against contractor bids and a realistic timeline, not just an optimistic one.
- Margin between all-in cost and projected exit value: Thin margins need more certainty elsewhere. Healthy margins can handle more uncertainty.
- A named, realistic backup exit: If the primary exit is a sale, what happens if the property sits for 90 extra days? Is there a refinance path, and does the borrower plausibly qualify?
- Local market absorption data: Days on market, inventory, and whether this property type is actually moving in that submarket right now.
- Borrower’s track record on similar projects: This predicts execution risk better than credit score.
- Title and entity structure: To confirm nothing clouds a clean sale or refinance at the end.
Red Flags
- No named exit, or an exit that changes depending on who’s asking (“sell or maybe rent, haven’t decided”).
- Projected ARV not supported by real closed comps, or relying on comps far outside the property’s area or condition.
- Renovation budget too thin for the stated scope of work.
- Refinance exit assumed without any pre-qualification or term sheet from the eventual lender.
- Thin or negative margin between all-in cost and projected exit value, with no buffer for delays or overruns.
- Borrower has no documented experience with the proposed exit (first flip, first refinance-and-hold, etc.) on a tight timeline.
- Market data shows slowing absorption or rising inventory in the price band and location, and the borrower’s plan doesn’t address it.
Before a lender reviews proof of liquidity, your file should be organized enough to answer basic underwriting questions quickly.
Borrower Readiness Checklist
- [ ] I can name my primary exit (sale, refinance, or payoff) in one sentence, with a realistic date.
- [ ] I have a backup exit if the primary one takes longer than planned.
- [ ] My projected ARV is supported by closed comps, not list prices or wishful thinking.
- [ ] My renovation budget matches a real contractor bid, not just a rough estimate.
- [ ] If my exit is a refinance, I’ve had a real conversation with that lender about qualification.
- [ ] I know my margin between all-in cost and projected exit value, and it has a reasonable cushion.
- [ ] I know what my local market’s absorption trends look like for this property type and price.
- [ ] If my credit is thin, I’ve considered whether sponsorship or tradeline support is relevant to my refinance exit, not just my acquisition loan.
FAQ
Does credit score matter at all in private money lending?
Yes, but it’s usually one factor among several, not the main gatekeeper. It matters more on refinance exits, sponsorship structures, and repeat-borrower pricing than on the initial bridge or acquisition loan.
What makes an exit strategy “strong” versus “weak” in a lender’s eyes?
A strong exit is specific, dated, and backed by evidence: real comps, a real contractor bid, a real refinance conversation already started. A weak exit is vague, undocumented, or depends on the market improving beyond what current data supports.
Can a borrower with bad credit still get funded on a good exit plan?
Often yes, for acquisition and bridge financing where the loan is secured by the asset and the exit. It gets trickier at the refinance stage if the permanent lender has hard credit requirements. That’s where credit-strengthening strategies come in.
What happens if the exit strategy fails mid-loan?
That’s why lenders want a backup exit before funding, not after. A sale that stalls can sometimes pivot to a refinance-and-hold, or vice versa, but only if that alternative was realistic from the start, not improvised under pressure near maturity.
Is this approach specific to one type of deal?
It applies mostly to fix-and-flip, bridge, and transactional funding where repayment ties to a specific, near-term event. Longer-hold rental financing relies more on debt-service coverage and conventional underwriting.
If you’re looking at a deal where the exit plan is solid but the credit picture is the sticking point, or want a second opinion on whether your numbers support your timeline, reach out to the team at JointVentureLoans.com. We underwrite the deal in front of us, not just the file behind it.
For related context, see The Ultimate Guide to Loan Sponsorship & Equity Partnerships for Real Estate Investors.
For related context, see Tradelines.
For related context, see Tradelines, Credit Sponsorship, and Loan Sponsorship: How Investors Qualify for Bigger Real Estate Deals.
For related context, see Tradelines, Credit Repair & Sponsorship: How Investors Boost Credit to Qualify for Deals.
For related context, see Loan Sponsorship for Multifamily Syndications: How Beginners Get Into Big Deals.
Further Reading and Source Context
These outside references can help you compare definitions, market language, and general real estate financing context. They are provided for education only and do not imply endorsement by those publishers: